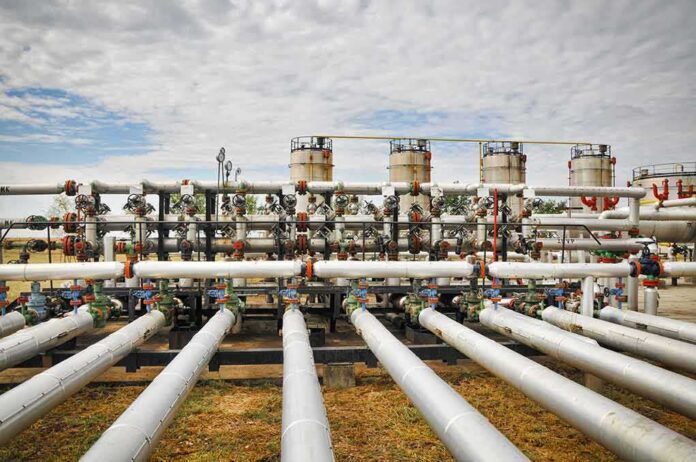
European natural gas briefly crossed €100 per megawatt-hour, signaling fresh winter risk for energy prices and supply.
Story Highlights
- Dutch TTF futures touched €100.30 per megawatt-hour, the highest since 2022.
- European Union storage sat around 75% in late October after a slow summer refill.
- Regulators linked higher prices to Middle East liquefied natural gas disruptions and lower storage.
- Market gains built for days as limited Gulf supplies tightened pre-winter positioning.
Prices Jump Past a Key Threshold
AFP reported that Dutch Title Transfer Facility futures rose about four percent and briefly hit €100.30 per megawatt-hour on October 28, the first touch of that level since 2022. Traders treat €100 as a warning sign because it pushes up power costs, fertilizer inputs, and home heating. Other reports in the same window showed prices near the mid to high €90s. That supports a sharp intraday spike, even if not a sustained close above €100.
Trading data over the prior sessions described steady gains tied to tight supply and winter demand. Market coverage said prices advanced past €88 and then past €96 as buyers secured fuel ahead of cold weather. Moves like these can feed on themselves when storage sits below normal and ship arrivals look uncertain. They also filter into bills for factories and families, which are already stretched by years of higher prices.
Storage Levels and Middle East Disruptions
The European Union Agency for the Cooperation of Energy Regulators said storage reached only 28 percent by the end of last winter, compared with 34 percent a year earlier. The agency said inventories were about 75 percent on October 21 after a slow summer refill. That leaves less cushion for cold snaps. The agency also tied the price rise to liquefied natural gas disruptions linked to conflict in the Middle East, which tightened supply and lifted prices.
The agency said Qatar-related exports through the Strait of Hormuz faced disruptions, which pushed Europe to rely more on other suppliers, especially the United States. At the same time, Qatari and Russian supplies fell. That mix forces Europe to bid harder in a global market for limited cargoes. When several regions chase the same shipments, prices jump even if physical shortages have not appeared yet. That is the dynamic hitting the benchmark now.
Why This Matters for American Readers
Higher European gas prices can spill into the United States through global liquefied natural gas trade. When Europe pays more, cargoes flow there, and that can firm world prices. American families feel it in electric bills where gas sets power prices, and in goods that need heat and power to make. U.S. energy strength helps blunt the shock. But tight foreign markets still tug on our costs, which is why steady domestic production and exports matter to both allies and U.S. wallets.
Policy choices in Europe also carry a lesson. Heavy bets on imports and slow restarts of firm generation make winters risky. When storage runs low and shipping lanes face conflict, prices surge. The European regulator’s note shows the chain: low post-winter stocks, slower summer refills, and liquefied natural gas hiccups tied to war. Solid, all-of-the-above energy and strong storage strategy protect families from that squeeze. America should not copy energy mistakes that raise bills and weaken security.
What to Watch Next
Traders will track fresh liquefied natural gas cargo schedules, ship traffic near the Strait of Hormuz, weather forecasts, and storage withdrawal rates. Norwegian pipeline flows and United States export runs may help replace some lost Qatari supply. If temperatures stay mild, pressure may ease. If cold weather hits early, prices can jump again. For now, the break above €100 shows the market is tight and nervous as winter nears, with clear links to storage and Middle East risk.
Sources:
insiderpaper.com, euronews.com, tradingeconomics.com